
Size of the US Crypto Market & The Need for Regulation
What Is the CLARITY Act & Why did it Fail?
It’s not over for the Clarity act: Democrats Pledge Bipartisan Support
Crypto Tax Bill Advances After Collapse of CLARITY Act
Strategic Bitcoin Reserve Bill Advances
Fed Interest Rate Hike and its Impact on the Crypto Market
The Way Forward for Crypto Regulation in the US

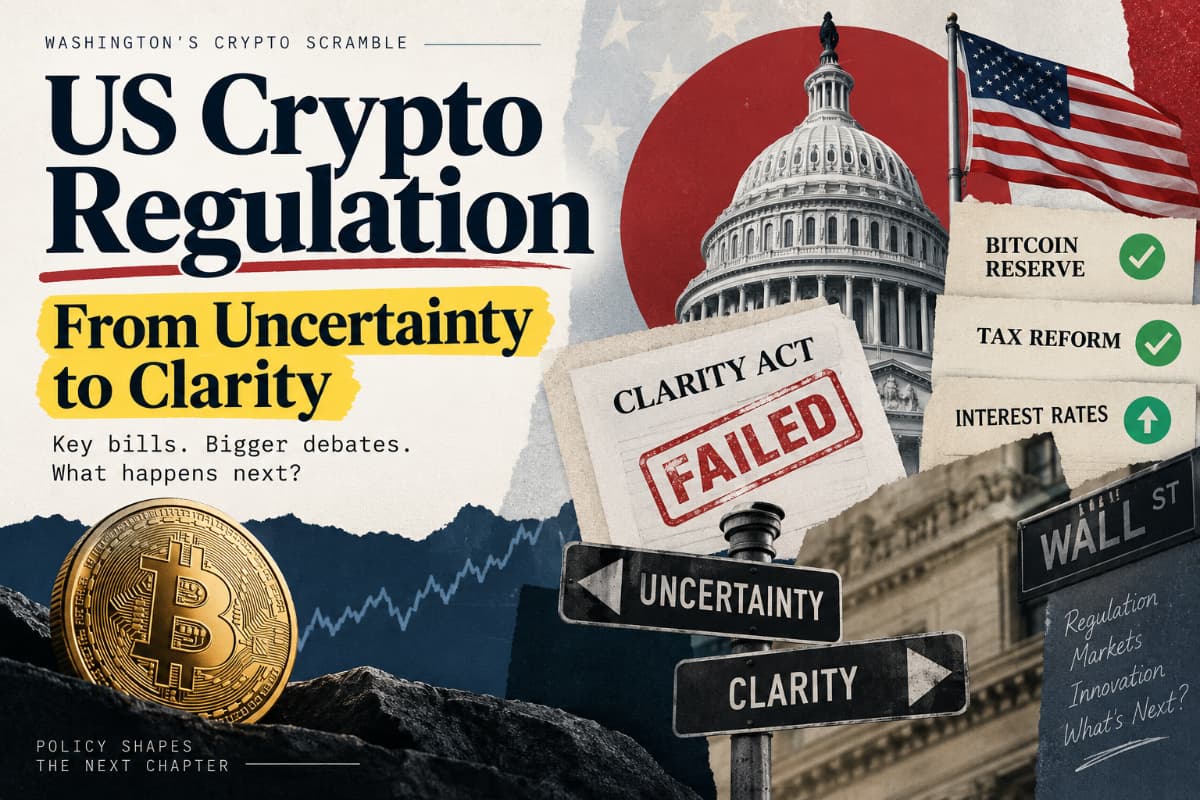
If you blinked this week, you missed a lot. In the space of about 72 hours, the Senate killed America's biggest crypto bill in years, a House committee quietly advanced a completely different one, lawmakers greenlit a plan to let the government hoard Bitcoin, and the Federal Reserve raised interest rates for the first time since 2023. Oh, and seven Democratic senators who'd just voted against a major crypto bill turned round the very next day and said they still want to pass it.
Confused? You're not alone. This issue walks through what actually happened, why it matters, and what might come next in plain English, with nothing left unexplained.
Start with the numbers, because they explain everything else. Roughly 67 million Americans about one in four adults now own some form of crypto, according to the National Cryptocurrency Association's 2026 survey, up from one in five just a year earlier. Other surveys land at slightly different figures, anywhere from a fifth to nearly a third of US adults, depending on how you ask the question, but they all point the same way: crypto has stopped being a niche hobby for tech bros and turned into something ordinary people hold alongside their pension and their mortgage.
Globally, the crypto market is worth around $2.29 trillion, not even counting stablecoins, which add a few hundred billion more on top. And the US isn't just a big player here, it's the single biggest one. Of the $85.3 billion that crypto exchanges and platforms are expected to earn worldwide in 2026, America alone accounts for $15.1 billion of it, more than any other country by some distance.
Here's the problem: a market this large, this mainstream, is still being run on rules that were never really designed for it. There's no single federal law that spells out how a crypto exchange should operate, who decides whether a token is a security or something else, or how customers' assets are meant to be protected if a platform goes under. Compare that to the stock market, where the rulebook has been settled for the best part of a century, and you can see why regulators, lawmakers and the industry itself have been pushing so hard for something clearer. That's the backdrop against which everything below happened.

The biggest attempt to fix that gap is a bill called the CLARITY Act (formally, the Digital Asset Market Clarity Act, H.R. 3633). To understand what it was trying to do, you need to understand a fight that's been running for years: whether a given crypto token counts as a security regulated by the Securities and Exchange Commission, the same body that oversees shares and IPOs or a commodity, regulated by the Commodity Futures Trading Commission, the body that oversees things like oil and wheat futures. For years, neither agency drew a clear line. The SEC, under previous leadership, mostly just sued companies after the fact rather than telling them the rules in advance, which the industry understandably found maddening.
CLARITY's fix was a “decentralisation test.” Put simply: if a blockchain network is genuinely open, running on published code, and not controlled by any single company or small group, the tokens on it think Bitcoin, and likely Ethereum would count as digital commodities and fall under the CFTC. Tokens still tightly controlled by a central team, the kind typically sold in a fundraising round, would stay under the SEC as securities. Stablecoins would get their own joint oversight arrangement (though the separate GENIUS Act already covers most of that ground).
On paper, this had real momentum. The House passed it back in July 2025 by a thumping 294–134, with 78 Democrats crossing the aisle to support it a genuinely bipartisan result in a Congress that agrees on almost nothing. The Senate Banking Committee approved its own version 15–9 in May 2026. Then, on September 15, 2026, it all fell apart. The procedural vote needed to open debate which requires 60 votes, it failed by 49–50. Not a single Democrat voted yes, and a handful of Republicans, including Josh Hawley and Thom Tillis, voted no as well.
What actually killed it wasn't the SEC/CFTC split at all lawmakers had largely made peace with that part. It was ethics. President Trump's family has reported well over a billion dollars in crypto-related income, and Democrats wanted much tighter rules stopping officials from profiting off the very market they'd be regulating. Republicans offered a compromise requiring senior officials to sell their crypto holdings or place them in a blind trust; Democrats wanted an outright sale requirement for large holdings, with no blind-trust loophole, and wanted the restrictions to cover officials' adult children too relevant given that Donald Trump Jr. and Eric Trump both have ties to the family's crypto venture, World Liberty Financial. Republicans wouldn't budge on the family-members point. Add in lingering disagreements over stablecoin rewards potentially draining deposits from small community banks, and who gets to enforce the new rules, and the coalition simply ran out of road.

Just one day after the vote failed, seven Democratic senators Kirsten Gillibrand, Angela Alsobrooks, Cory Booker, Catherine Cortez Masto, Ruben Gallego, Mark Warner and Raphael Warnock put out a joint statement that struck a very different tone from the vote itself: “This week was a setback, but not the end of that important work. We remain committed to working in a bipartisan fashion to get this legislation passed.”
It wasn't the first time this particular group had said something similar six of the seven made nearly identical noises back in July, when they rejected an earlier Republican draft as falling short on ethics. What makes these seven senators worth watching is simple arithmetic: they're roughly the bloc Republicans need to find nine votes from to reach 60. The statement offered no new concessions and no timeline, which tells you the two sides are still a fair distance apart. And time is tight the Senate breaks for recess in early October and won't return until after the November 3 midterms, an election that could easily reshuffle who controls Congress and reset the entire negotiation from scratch.
Interestingly, the very same week CLARITY collapsed, a completely different crypto bill was quietly sailing through committee. The House Ways and Means Committee advanced the Digital Asset Tax Certainty Act (H.R. 10357) by 38 votes to 5 with only five Democrats opposed, making it, by Washington's current standards, almost uncontroversial.
The bill tidies up several genuinely annoying quirks in how crypto gets taxed today. It exempts small transaction fees from triggering a taxable event, makes it easier to actually spend crypto or stablecoins on everyday purchases without a tax headache every time you buy a coffee, treats staking and mining rewards as ordinary income rather than a separate capital-gains puzzle, and tightens the rules around quickly rebuying a similar asset just to book a paper loss. Committee chairman Jason Smith called it “the first-ever tax framework for digital assets,” which, provisions aside, is a fair description of the milestone itself.
The catch: it's only cleared one committee. A full House vote likely won't happen until after the midterms, and if Democrats retake the House in November, the bill could easily get shelved before it ever reaches the floor.
As if two crypto bills in one week wasn't enough, the House Financial Services Committee also advanced the American Reserve Modernization Act (H.R. 8957) by 28 votes to 21, formally writing President Trump's Strategic Bitcoin Reserve into law rather than leaving it as an executive order.
The bill sets up a Treasury-run Strategic Bitcoin Reserve, plus a separate Digital Asset Stockpile for other tokens the government picks up through criminal or civil forfeiture things like Ethereum, XRP, Solana and Cardano. Any Bitcoin that goes in has to stay put for a minimum of 20 years, with quarterly “proof of reserve” audits so nobody has to simply take the government's word for what it holds. States would even be allowed to park their own Bitcoin holdings inside the same federal structure. And in a nod to crypto's libertarian roots, the bill goes out of its way to protect ordinary citizens' right to self-custody that is, to hold their own private keys without government interference.
Why does this matter? The US government already holds an estimated 324,500-odd Bitcoin worth roughly $24.7 billion scattered across various agencies with, by most accounts, wildly inconsistent security practices. This bill is essentially a tidy-up job, giving all that Bitcoin one proper home with one set of rules. It still needs to clear the full House, the Senate, and get a presidential signature before it's actually law, so there's a way to go yet but of the three bills in this issue, it's arguably the one with the smoothest path ahead.

Just to make sure nobody had a quiet week, the Federal Reserve raised interest rates by 0.25 percentage points on September 16, 2026, taking its target range to 3.75–4.00%. It was the first rate rise since 2023, and the Federal Open Market Committee voted for it unanimously under Chair Kevin Warsh.
The reasoning was straightforward: the labour market has stayed strong enough that the Fed felt able to turn its full attention back to inflation, which remains stubbornly above its 2% target and, on the Fed's own projections, won't get back there until 2029. “The plain fact is that inflation is too high and has been for too long,” Warsh said. The Fed's forecasts even hint at one more quarter-point rise before the year is out.
Crypto's reaction was muted rather than dramatic. Bitcoin dipped about 0.2%, Ethereum barely moved, and XRP fell just over 2%, but the wider market excluding stablecoins was still up 0.8% over the same 24 hours, sitting around $2.29 trillion. Why does a rate hike matter for crypto at all? Because when it's easy to earn a safe, decent return just by holding cash or government bonds, investors have less reason to take on the extra risk that comes with something as volatile as crypto. Rates staying “higher for longer,” with no cuts currently pencilled in for 2027, won't necessarily crash the market but it could quietly put a ceiling on how far any recovery goes.

Stand back, and the pattern is hard to miss. In a single week, the US tried three different ways of bringing crypto in from the regulatory cold a comprehensive market-structure bill, a tax-clarity bill, and a narrower bill just for the government's own Bitcoin holdings and only the narrowest one is moving without a major fight.
The big one, CLARITY, is stuck until either a fresh compromise emerges on ethics and divestment, or the midterms reshuffle the numbers in the Senate enough to change the maths entirely. Realistically, that pushes any comprehensive deal into 2027 at the earliest. In the meantime, without legislation, it's the SEC and CFTC who get to fill the gap through their own rulemaking rather than Congress which means the old pattern of “regulation by enforcement,” where the line between a security and a commodity gets decided case by case, court by court, is likely to continue for a while yet.
For anyone holding, trading or building in crypto, the practical takeaway is this: don't expect a clean, comprehensive rulebook any time soon. Watch the November midterms as the real reset moment for the CLARITY Act, keep an eye on the narrower tax and Bitcoin-reserve bills as the more likely near-term movers, and don't discount interest rates as part of the story either a market that used to run almost entirely on regulatory headlines and halving cycles is increasingly reacting to Fed decisions the way any other risk asset would. Worth putting the FOMC calendar next to the Congressional one from here on.
India Crypto Research operates independently. The information presented herein is intended solely for educational and informational purposes and should not be construed as financial advice. Before making any financial decisions, it's essential to undertake your own thorough research and analysis. If you're uncertain about any financial matters, we strongly recommend seeking guidance from an impartial financial advisor.


